Introduction
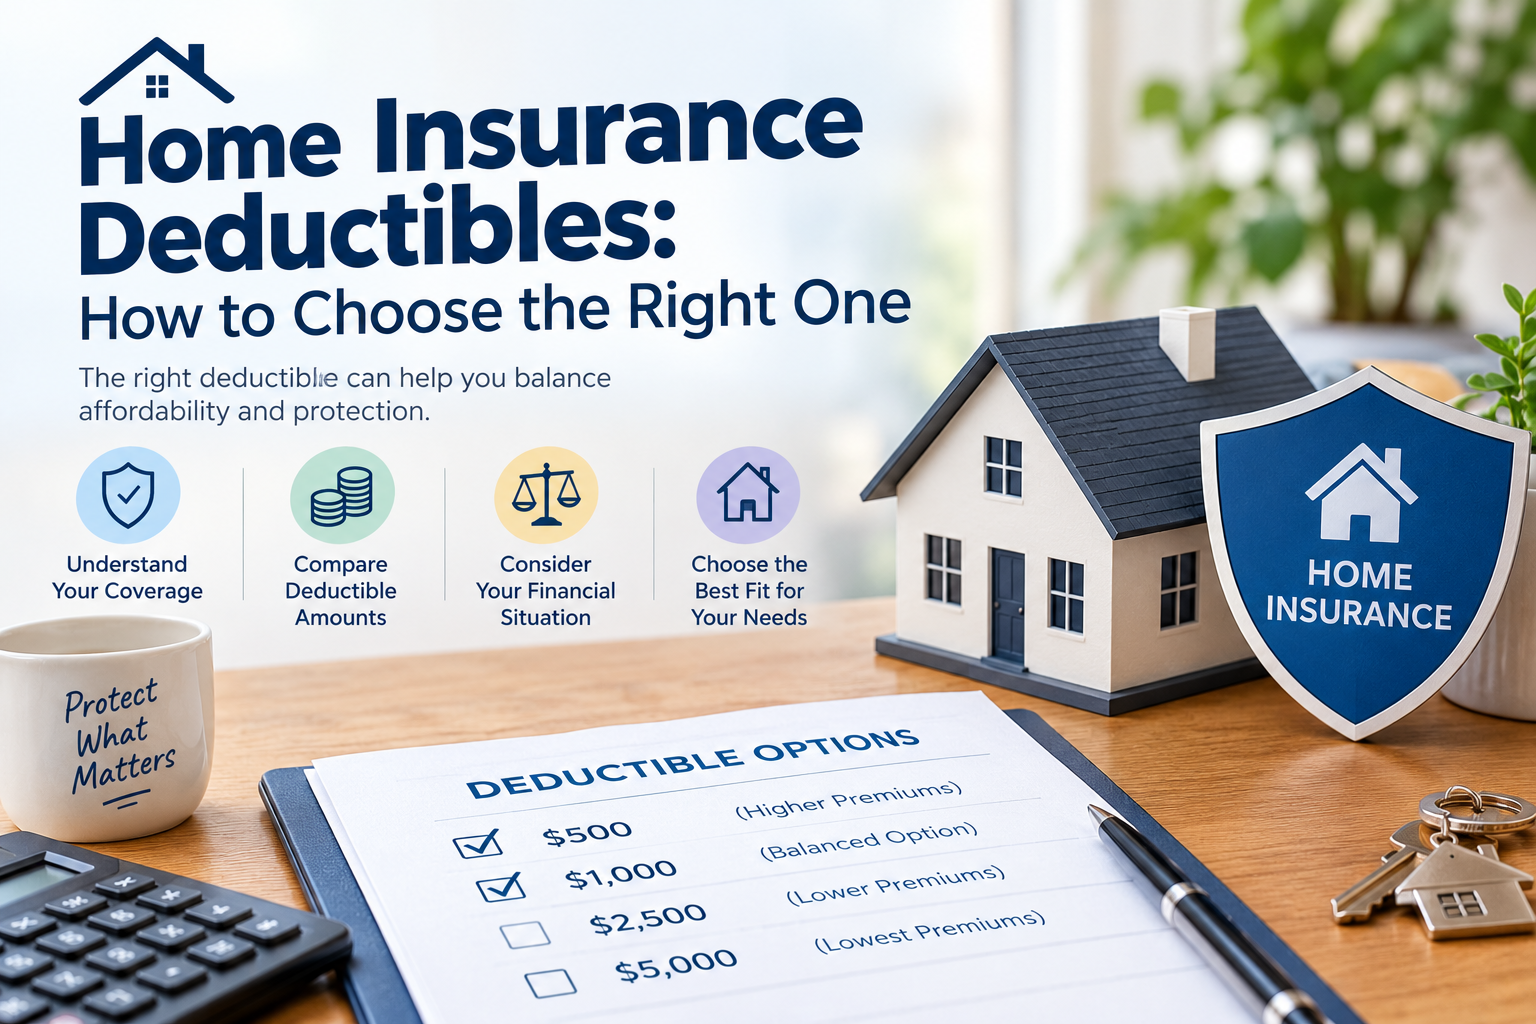
Choosing the right home insurance deductible can help you balance affordable premiums with financial protection. A lower deductible usually means paying more for insurance each month or year, while a higher deductible may reduce your premium but leave you responsible for more repair costs after a covered loss. The best option depends on your savings, household budget, property risks, and policy terms.
Understanding Insurance Deductibles is especially important before buying a policy or renewing your existing coverage. A deductible that looks affordable on paper may become difficult to manage after a storm, fire, or other unexpected event. By comparing your options and reviewing the details of your policy, you can make a decision that suits your financial situation.
What Is a Home Insurance Deductible?
A home insurance deductible is the amount you must pay toward a covered property claim before your insurer pays the remaining eligible amount, subject to your policy limits and conditions. For example, if covered repairs cost $8,000 and your deductible is $1,000, your insurer may pay $7,000. This assumes the entire repair cost is covered and no other limits or adjustments apply.
Insurance Deductibles generally apply to covered damage to your home or personal belongings. However, the amount and method of calculation can vary between policies and countries. Some policies use a fixed amount, while others apply a percentage to the insured value of your property.
The deductible is different from your insurance deductible premium. Your premium is the amount you pay to maintain coverage, whereas the deductible is your share of an eligible claim. Understanding both costs helps you compare policies more accurately.
Types of Home Insurance Deductibles
Fixed-Dollar Deductibles
A fixed-dollar deductible is a specific amount stated in your policy. Common examples include $500, $1,000, and $2,500, although available options depend on the insurer and location. Suppose your kitchen suffers $4,000 in covered fire damage. With a $500 deductible, your potential claim payment would be $3,500. With a $1,500 deductible, the payment would be $2,500.
The lower deductible reduces your share of the repair bill but it may come with a higher premium. Compare the actual premium difference before deciding whether the extra cost is worthwhile.
Percentage-Based Insurance Deductibles
Some policies calculate Insurance Deductibles as a percentage of the insured dwelling amount rather than a fixed dollar figure. These deductibles may apply to specific risks, such as windstorms, hail, hurricanes, or named storms. For example, if your home is insured for $250,000 and your policy has a 2% storm deductible, you would be responsible for $5,000 for a covered loss subject to that deductible.
This is an important distinction because a percentage can produce a much larger out-of-pocket expense than you might expect. Always check whether the percentage applies to your dwelling coverage limit or another amount specified in the contract.
Separate Disaster Deductibles
Some homeowners policies contain different deductibles for particular events. A standard deductible may apply to many covered claims, while a separate windstorm, hurricane, or hail deductible applies to certain weather-related damage.
Do not assume that every type of damage uses the same deductible. Flood and earthquake damage may also require separate coverage, depending on the policy and country. A deductible does not make an excluded event covered.
How to Choose the Right Deductible
Assess Your Emergency Savings
Your savings are one of the most important factors when selecting Insurance Deductibles. Ask yourself how much money you could access quickly if your roof needed repairs or a burst pipe damaged your home.
If paying $2,500 at short notice would force you to borrow money or miss essential bills, a lower deductible may be more suitable. If you have a strong emergency fund and can comfortably cover a larger unexpected expense, a higher deductible may be worth considering.
Avoid using all your available savings to reduce your premium. You may still need money for temporary accommodation, uncovered repairs, or other emergencies.
Compare Premium Savings With Potential Costs
A higher deductible can reduce your premium, but the savings should justify the additional financial risk. Imagine that one policy costs $1,500 per year with a $500 deductible, while another costs $1,350 per year with a $1,500 deductible. The second policy saves $150 annually but requires an additional $1,000 if you make a covered claim.
At that savings rate, it would take about 6.7 years without considering claim frequency, premium changes, or the time value of money to accumulate $1,000 in premium savings. This example shows why the cheapest annual premium is not always the best overall choice. Request quotes with several deductible options and compare the total cost rather than focusing on the premium alone.
Consider Your Home’s Location and Risks
Your location can affect both the cost of coverage and the deductible options available. Homes exposed to hurricanes, hailstorms, wildfires, or other local hazards may face different policy terms from properties in lower-risk areas.
Review the events most likely to affect your property. If severe storms are common in your region, pay particular attention to separate weather-related deductibles and exclusions. If flooding is a concern, confirm whether flood coverage is included or must be purchased separately. Choose Insurance Deductibles only after understanding the risks your policy actually covers.
Review Your Policy’s Coverage Limits
A deductible is only one part of a homeowners policy. You should also check dwelling coverage, personal property protection, liability coverage, exclusions and whether repairs are paid on a replacement-cost or actual-cash-value basis.
Replacement-cost coverage generally considers the cost of repairing or replacing covered property without deducting depreciation, subject to policy terms. Actual-cash-value coverage typically accounts for depreciation. These differences can affect your final claim payment. A manageable deductible cannot compensate for insufficient coverage or an excluded loss.
Benefits and Risks of Higher Deductibles
The main benefit of a higher deductible is the potential to lower your insurance deductibles premium. It may suit homeowners who have sufficient savings and want to reduce recurring expenses. Higher Insurance Deductibles may also encourage people to handle minor repairs themselves rather than submitting small claims. However, you should never avoid reporting a loss when your policy or local rules require notification, and you should consider the risk of worsening damage.
The main disadvantage is the larger amount you must pay after a covered incident. A high deductible can create financial pressure if several unexpected expenses occur together. Premium discounts also vary by insurer, so increasing your deductible may not produce enough savings to justify the extra risk.
A lower deductible offers more predictable out-of-pocket costs for covered claims, but the higher premium can place greater pressure on your regular budget. Neither option is automatically best for every household.
Common Mistakes to Avoid
One common mistake is choosing the highest available deductible simply to obtain a lower premium. Before making that choice, confirm that you could pay it without relying on expensive credit.
Another mistake is overlooking percentage-based storm deductibles. A small percentage of a home’s insured value can translate into thousands of dollars. Read your policy declarations and ask your insurer to explain any separate deductibles in plain language.
Do not compare policies based on price alone. Check coverage limits, exclusions, claims procedures, and the insurer’s service record. Also, review your coverage whenever you renovate your home, change your financial circumstances, or renew your policy.
A Practical Checklist Before You Decide
Before selecting Insurance Deductibles, estimate how much you could comfortably pay from savings after an unexpected loss. Then request quotes showing the premium for several deductible amounts.
Read the policy declarations to identify standard and special deductibles. Confirm how percentage-based amounts are calculated and which events trigger them. Check whether flood or earthquake protection requires separate insurance.
Finally, compare the potential premium savings with the extra amount you would have to pay for a claim. Ask the insurer or a qualified insurance professional to clarify any terms you do not understand. Keep a copy of the policy and make sure household members know where to find it.
Frequently Asked Questions
Q1. What is the best home insurance deductible?
The best deductible is one that balances affordable premiums with an out-of-pocket amount you can comfortably pay. Your savings, property risks and available policy options should guide your decision.
Q2. Does a higher deductible lower home insurance premiums?
Often, yes. Insurers may charge lower premiums when you agree to pay more toward a covered claim. However, the actual savings depend on the insurer, property, location and policy.
Q3. Can I choose a different deductible for storm damage?
Some policies allow or require separate deductibles for wind, hail, hurricanes, or named storms. Availability and rules vary by location, so check your policy documents carefully.
Q4. Do I pay my deductible for every claim?
Generally, a deductible applies to each covered claim, but the exact rules depend on your policy and the type of loss. Certain policies may have special conditions or separate deductibles.
Q5. Should I choose a $500 or $1,000 deductible?
Compare the premium difference and decide whether you could comfortably pay either amount after a loss. If the higher deductible produces only a small saving, the lower option may offer better value for your circumstances.
Final Thoughts
Choosing the right home insurance deductible requires more than finding the lowest premium. You need to understand how claims are calculated, which risks are covered, and how much you could pay without disrupting your finances.
Review your savings, compare quotes, and pay close attention to percentage-based and disaster-specific deductibles. The right balance can help you maintain useful home protection while keeping insurance costs manageable.
Insurance Deductibles should fit your financial circumstances rather than force you to take risks you cannot afford. Before purchasing or renewing a policy, read the terms carefully and seek clarification from your insurer when necessary.
2 thoughts on “Home Insurance Deductibles: How to Choose the Right One”