Introduction
Running a business comes with different responsibilities and financial risks. If you operate a small shop, manage a service company, work as a contractor or run an online business, unexpected accidents can create expensive problems. A customer might slip on your premises, a product could accidentally damage someone’s property or your business activities could result in a personal injury claim.
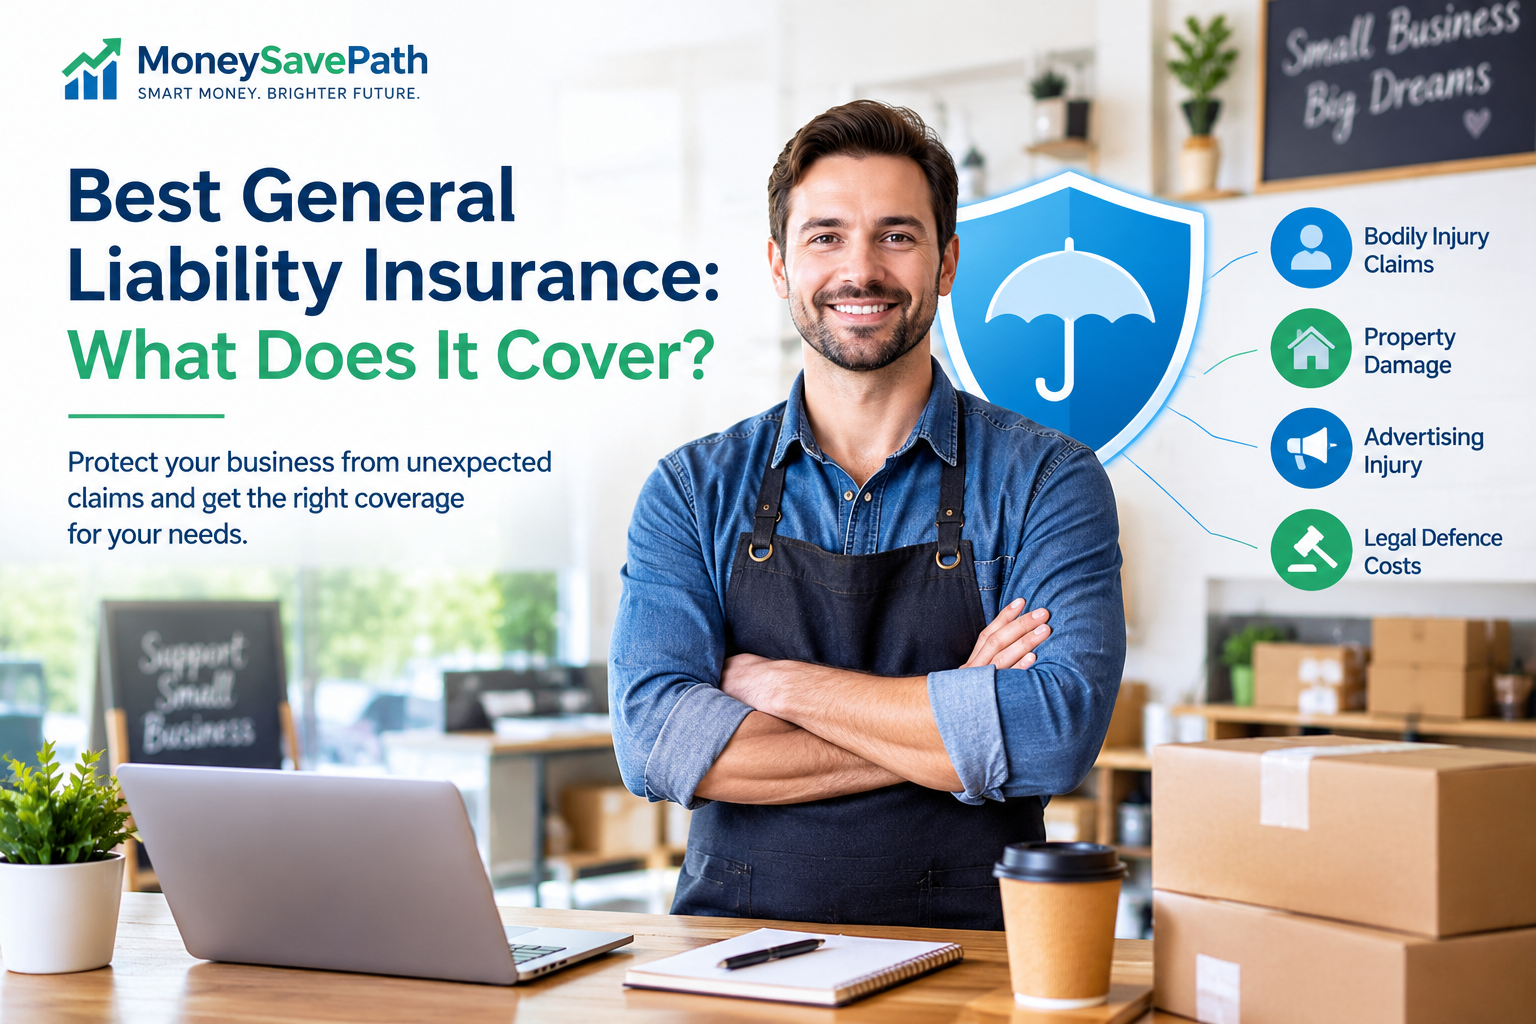
This is where General Liability insurance can help. It is a type of business insurance designed to protect companies against certain third-party claims involving bodily injury, property damage, and personal or advertising injury. It can also help cover legal defence costs when a covered claim arises.
Understanding General Liability coverage is important before choosing a policy. Different insurers offer different protection limits, exclusions, and conditions. This guide explains what this insurance covers, how it works, its benefits and what business owners should consider before purchasing a policy.
What Is General Liability Insurance?
General Liability insurance is a business insurance policy that helps protect a company against certain claims made by customers, visitors, suppliers or other third parties. These claims may involve physical injuries, property damage or specific personal and advertising-related offences connected with business activities.
For example, imagine a customer visits your retail store and slips on a wet floor. If the customer suffers an injury and claims that your business was responsible, the policy may help cover eligible medical expenses, legal defence costs or a settlement, depending on its terms.
This type of protection is particularly useful for businesses that interact with customers, work at client locations, sell products or operate commercial premises. However, General Liability insurance does not cover every business risk. It is important to understand the policy wording, coverage limits, exclusions and local insurance requirements before making a decision.
What Does General Liability Insurance Cover?
The exact protection depends on the insurer and policy. However, standard commercial general liability policies commonly include several important coverage areas.
Bodily Injury Claims
One of the main purposes of General Liability coverage is to protect businesses against certain third-party bodily injury claims. These incidents may happen when someone is injured because of an alleged failure to maintain safe business premises or other covered business activities.
For example, a visitor might trip over loose flooring in your office and suffer an injury. If the business is legally responsible, the insurance may help pay covered medical expenses, legal defence costs and compensation. Coverage depends on the circumstances and policy conditions.
Property Damage Claims
Businesses sometimes cause accidental damage to property belonging to customers or other third parties. Property damage coverage can help protect against certain resulting financial claims. For example, imagine a plumbing contractor accidentally damages a customer’s flooring while repairing a pipe. The customer may request compensation for the repair costs.
A suitable General Liability policy may cover eligible property damage claims, subject to exclusions and conditions. This protection can be valuable for contractors, maintenance companies, cleaning services and businesses that work at customer locations.
Personal and Advertising Injury
Another important coverage area involves certain non-physical injuries connected with business activities.
Depending on the policy, personal and advertising injury coverage may include claims involving:
- Libel or slander.
- Certain privacy violations.
- Copyright infringement in advertising materials.
- Certain wrongful eviction or invasion of privacy claims.
For example, a company might publish an advertisement that allegedly uses another business’s protected advertising material without permission. The affected business could bring a claim. A General Liability policy may provide protection for certain advertising injury claims but not every intellectual property dispute is covered.
Legal Defence Costs
Defending a business against a lawsuit can be expensive, even when the company believes it has done nothing wrong. Covered legal defence costs are therefore an important feature of many commercial liability policies. Depending on the policy, an insurer may appoint legal professionals and pay eligible defence expenses.
For example, if a customer files a lawsuit after an accident at your business premises, your insurer may investigate the incident and arrange legal representation. However, defence costs may be handled differently depending on the policy. They may be included within the coverage limit or paid in addition to it.
Who Needs General Liability Insurance?
General Liability insurance can be useful for businesses of different sizes and industries. Although coverage needs vary, companies that regularly interact with customers or third parties may benefit from this protection.
Common examples include:
Small businesses: Retail stores, restaurants, salons and offices may face customer injury or property damage claims.
Contractors: Builders, electricians, plumbers and maintenance professionals may accidentally damage customer property while performing work.
Freelancers and consultants: Professionals who visit client locations or work with customers may face certain third-party liability risks.
Online businesses: E-commerce companies may face product-related liability claims or advertising injury allegations, depending on their activities and policy terms.
Service providers: Cleaning companies, event organisers, and marketing agencies may benefit from protection against certain third-party claims.
Not every business needs identical coverage. Companies should assess their operations, contractual responsibilities, customer interactions and potential financial exposure.
What Does General Liability Insurance Not Cover?
Although General Liability insurance provides useful protection, it does not cover every financial problem a business might experience. Understanding common exclusions helps business owners avoid unexpected coverage gaps.
Some common exclusions include:
Employee injuries: Injuries or illnesses suffered by employees while working generally require workers’ compensation insurance or equivalent local coverage.
Professional mistakes: Errors in professional advice, consulting, accounting or other specialised services may require professional liability insurance.
Damage to business property: Theft, fire or damage to your own office equipment, furniture and inventory generally requires commercial property insurance.
Business vehicle accidents: Accidents involving vehicles used for business purposes usually require commercial auto insurance.
Cyberattacks and data breaches: Losses involving stolen customer information, hacking, or compromised digital systems generally require cyber insurance.
Intentional damage: Deliberate harmful actions are generally excluded from standard liability coverage.
These exclusions demonstrate why businesses may need several insurance policies rather than relying on one. For example, a consulting company might need both General Liability and professional liability insurance to address different types of third-party claims.
How Much General Liability Insurance Does a Business Need?
The appropriate amount of General Liability coverage depends on the nature of your business, its size, daily activities, customer interactions and potential financial exposure. A small home-based business may have different insurance needs from a construction company that regularly works on large commercial properties.
Consider these factors when choosing coverage:
- Business activities: Companies with frequent customer visits or physical operations may face greater third-party liability exposure.
- Customer contracts: Some clients, landlords, and commercial partners require specific liability limits before allowing a business to operate or begin work.
- Industry risks: Contractors, retailers, restaurants, and manufacturers may face different types of claims.
- Financial exposure: Consider whether your business could manage a large legal claim without insurance.
- Policy limits: Review both per-occurrence and aggregate limits to understand the maximum protection available.
For example, a contractor working on expensive properties may need higher coverage limits than a freelancer who mainly works remotely. There is no single coverage amount that suits every business. Compare insurance options and consult a qualified insurance professional before selecting a policy.
How to Choose the Best General Liability Insurance
Finding the right policy requires more than comparing premium prices. A cheaper option may have lower limits, restrictive exclusions or coverage conditions that do not suit your business. Here are some practical steps to consider.
Compare Coverage and Policy Limits
Review what each insurer includes in its General Liability policy. Check bodily injury, property damage, personal and advertising injury and any additional coverage options.
Pay attention to per-occurrence limits and aggregate limits. These explain how much the insurer may pay for an individual covered incident and all covered claims during the policy period.
Understand Exclusions and Conditions
Read the policy documents carefully before purchasing coverage. Some policies include exclusions that may affect particular industries, products, activities or contractual responsibilities.
Ask the insurer to explain anything you do not understand.
Check the Insurer’s Reputation
Research the insurer’s financial strength, customer service, claims process and complaint history. A reliable provider should explain coverage clearly and provide accessible support when you need assistance.
Compare Premiums and Deductibles
Request quotes from multiple insurance providers. Compare the premiums, deductibles, limits, exclusions and payment conditions rather than choosing the cheapest policy automatically.
Review Coverage Regularly
Your business may change over time. New employees, additional locations, different products and larger contracts can create new insurance requirements.
Review your General Liability policy regularly and update it when your business activities change.
Benefits and Limitations of General Liability Insurance
One major benefit of General Liability insurance is financial protection against certain third-party claims. Without suitable coverage, a business may need to pay legal expenses, settlements or damages using its own resources. It can also improve business credibility. Some customers, landlords and commercial partners prefer or require proof of liability insurance before signing contracts.
However, there are limitations. Premiums add to operating expenses, claims are subject to policy conditions, and exclusions may leave some risks uninsured. Coverage limits can also be insufficient for particularly large claims. Business owners should treat liability insurance as part of a wider risk management plan rather than a replacement for workplace safety, proper contracts, staff training and other necessary insurance policies.
Frequently Asked Questions (FAQs)
Q1. What does general liability insurance cover?
General Liability insurance generally covers certain third-party claims involving bodily injury, property damage, and personal or advertising injury. It may also cover eligible legal defence costs and medical expenses, depending on the policy terms.
Q2. Is general liability insurance required for small businesses?
Requirements vary by country, industry, and business activities. Some clients, landlords, and commercial contracts require businesses to maintain liability insurance. Check local regulations and contractual obligations before operating.
Q3. Does general liability insurance cover employee injuries?
Generally, no. Employee workplace injuries are usually handled through workers’ compensation insurance or an equivalent policy required by local law.
Q4. How much does general liability insurance cost?
The cost depends on several factors, including business type, location, annual revenue, number of employees, claims history, coverage limits and selected policy options. Request quotes from multiple insurers to compare prices.
Q5. Is general liability insurance worth it for a small business?
It can be valuable because even a single third-party injury or property damage claim may create significant legal and financial expenses. The right policy can help protect business finances against eligible claims.
Final Thoughts
General Liability insurance is an important consideration for businesses that interact with customers, provide services, sell products, or operate commercial premises. It can provide financial protection against certain third-party injury, property damage and advertising injury claims.
However, every policy has limitations, exclusions, and coverage conditions. Business owners should compare insurers, review policy documents, and consider additional protection such as professional liability, commercial property, workers’ compensation, and cyber insurance.
Choosing suitable coverage can help your business manage unexpected risks and operate with greater financial confidence. Take time to understand your business requirements before purchasing a policy.