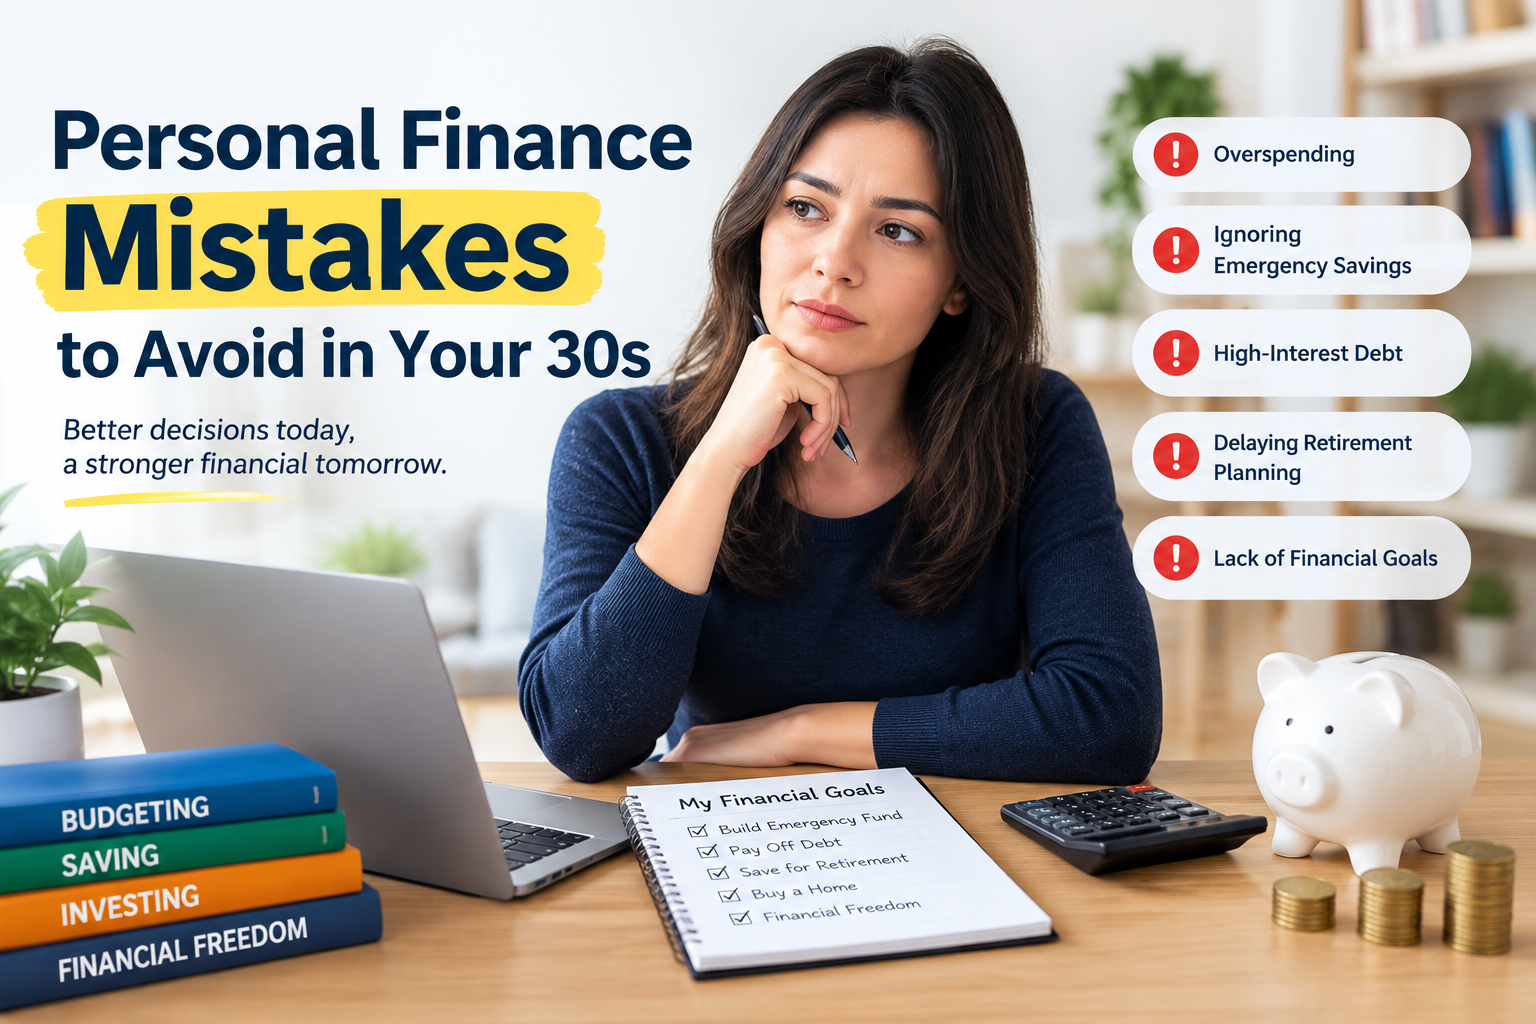
Your 30s can be an important time for building a stable financial future. You may be earning more than you did in your 20s while managing new responsibilities such as rent or a mortgage, family expenses, career growth, and retirement planning. These changes can make money management more challenging.
Many people make Finance Mistakes because they focus on their current lifestyle without giving enough attention to their long-term needs. Others delay saving because they believe they need a higher income before they can make progress. Both habits can make future financial goals harder to reach.
The good news is that you do not need a perfect financial record to improve your situation. You can start with a clear budget, manageable savings goals, and a practical plan for debt and investments. Understanding common Finance Mistakes can help you make informed decisions and use your income more effectively.
Ignoring Your Monthly Budget
One of the most common Finance Mistakes is spending money without knowing where it goes. Small purchases, subscriptions, restaurant meals and online shopping can gradually consume a large part of your income. A budget helps you understand your income and expenses. Start by recording your monthly earnings and essential costs such as housing, food, transportation, utilities, and debt payments. Then review discretionary spending and decide how much you can save.
For example, if you earn $3,500 per month and spend $3,350, you have only $150 left for savings and unexpected expenses. Finding ways to reduce unnecessary spending by $200 could increase your available savings to $350. Your budget should reflect your real circumstances. A simple spreadsheet or budgeting app can help you track progress without making money management unnecessarily complicated.
Delaying Emergency Savings
Another serious finance mistakes is assuming that unexpected expenses will somehow take care of themselves. Car repairs, medical bills, home maintenance or a temporary loss of income can disrupt even a well-planned budget. An emergency fund gives you money to handle these events without immediately relying on credit cards or loans. The Consumer Financial Protection Bureau explains that emergency savings can help people manage unexpected costs and reduce the need to borrow.
Start with a small, achievable target if saving several months of expenses feels difficult. You could initially aim for $500 or $1,000, depending on your circumstances and gradually build a larger reserve. Keep emergency savings accessible and separate from everyday spending. A suitable savings account may provide both convenience and some interest, although rates and account protections vary by country.
Carrying High-Interest Debt for Too Long
Credit cards and personal loans can help cover expenses when used carefully. However, allowing high-interest balances to grow is one of the Finance Mistakes that can restrict your financial choices for years. Interest increases the total amount you repay. When a large portion of your monthly payment goes toward interest, reducing the original balance can become difficult.
List your debts with their balances, interest rates, and minimum payments. Continue making required payments while directing extra money toward the debt with the highest interest rate. This approach can reduce interest costs, although some people prefer the debt snowball method because clearing smaller balances first can provide motivation. Avoid taking on new debt without considering its full cost. Compare interest rates, fees, repayment periods, and penalties before agreeing to a loan.
Waiting Too Long to Start Retirement Planning
Retirement may seem far away in your 30s, especially when you have immediate expenses. However, postponing retirement planning means missing opportunities to benefit from long-term investment growth. Compound growth occurs when returns generate additional returns over time. Starting earlier gives your savings more time to grow, but investment returns are never guaranteed.
For example, regularly contributing a manageable amount to a retirement account can help you build a habit that grows with your income. If your employer offers a retirement contribution match, check the eligibility rules and consider if you can take advantage of it. Review available retirement accounts, tax rules, fees and investment choices in your country. You do not need to contribute a large amount immediately. Consistency and a realistic plan matter more than waiting for the perfect time to begin.
Increasing Spending Every Time Your Income Rises
A salary increase can improve your quality of life, but spending all of it immediately can prevent you from making financial progress. This pattern is often called lifestyle inflation. For example, a promotion may encourage you to purchase a more expensive car, move into a costlier home, or increase your regular entertainment spending. These choices are not automatically wrong, but higher recurring expenses can reduce the money available for savings and debt repayment.
When your income rises, consider directing part of the increase toward emergency savings, retirement, or high-interest debt. You can still use some of the extra income for things you enjoy. The goal is balance. Avoiding Finance Mistakes does not mean eliminating every enjoyable purchase. It means making sure your lifestyle remains affordable while your future needs receive attention.
Investing Without Understanding the Risks
Investing can help you work toward long-term goals, but putting money into products you do not understand can expose you to avoidable losses. Some beginners follow social media trends, buy assets because friends recommend them, or invest because they fear missing an opportunity. Promises of high returns with little or no risk are also common warning signs of investment fraud. Before investing, identify your goals, time horizon, and ability to tolerate losses. Learn about diversification, investment fees, and the differences between cash savings and market-based investments.
Diversification means spreading investments across different assets rather than depending entirely on one company or market. It can help manage certain risks, but it cannot guarantee profits or prevent all losses. Do not invest money needed for near-term essential expenses. Research investments carefully and check the registration and background of finance mistakes l professionals through the appropriate regulator in your country.
Neglecting Insurance and Financial Protection
Building savings and investments is important, but protecting yourself against major finance mistakes setbacks also matters. A serious illness, accident, property loss or death in the family can create costs that ordinary savings may not cover. Review your existing insurance and identify the risks that could cause significant financial hardship. Depending on your circumstances, relevant coverage may include health, life, home, renters, disability or motor insurance.
Do not choose a policy based on price alone. Compare coverage limits, exclusions, deductibles, waiting periods and claim conditions. A cheaper policy may offer less protection, while a more expensive policy may include benefits you do not need. Insurance requirements and available products differ across countries. Review local rules and compare policies carefully before making a decision.
Failing to Set Clear Financial Goals
Without clear goals, it can be difficult to decide which financial priorities deserve your attention first. Saving, investing, buying a home, paying off debt and supporting family members may all compete for the same income. Write down your short-term and long-term goals. A short-term goal might be saving for an emergency or paying off a credit card. A long-term goal could be funding retirement or buying a home.
Give each goal a target amount and a realistic timeline. For example, saving $1,200 over twelve months requires setting aside $100 per month, before any interest earned. Review your goals when your income, expenses, or family responsibilities change. A flexible plan is often more useful than a strict target that no longer fits your circumstances.
Ignoring Credit Reports and Financial Fees
Credit reports, account fees, loan charges, and investment expenses can affect your financial position. Ignoring them may lead to errors, unnecessary costs or missed opportunities to improve your credit history. Check your credit report through the official service available in your country. Look for unfamiliar accounts, incorrect information, and signs of possible identity theft. If you find an error, follow the relevant provider’s formal dispute process.
Review bank statements and financial product terms as well. Monthly account fees, overdraft charges, late-payment penalties, and investment management fees may appear small individually but can add up over time. Do not assume every fee is avoidable or every paid product is poor value. Compare the cost with the service provided and switch only when an alternative meets your needs.
Comparing Your Financial Progress With Others
Social media can make it seem as though everyone in their 30s owns a home, travels regularly, earns a high salary, and has substantial investments. Comparing your finances with these impressions can lead to unnecessary spending or risky decisions. People have different incomes, family obligations, living costs, health needs, and access to financial support. Someone else’s lifestyle does not reveal their savings, debts, or financial security.
Focus on measurable progress instead. You might aim to reduce a loan balance, build emergency savings, increase retirement contributions, or avoid unnecessary fees. One of the most useful ways to prevent Finance Mistakes is to make decisions based on your own circumstances rather than outside pressure. Progress may be gradual, but consistent improvements can strengthen your financial position.
How to Improve Your Finances Starting Today
You do not need to fix every finance mistakes issue at once. Begin by reviewing your current position, including income, regular expenses, savings, debts and existing insurance. Choose one or two priorities for the next month. You might set up an automatic savings transfer, review recurring subscriptions, or create a repayment plan for high-interest debt. Small steps are easier to maintain when they fit your budget.
Next, schedule a monthly financial review. Check whether your spending matches your plan, whether your savings are growing, and whether any upcoming expense needs attention. Adjust your goals when necessary rather than treating your first budget as permanent. Learning about personal finance mistakes is an ongoing process. Reliable educational resources, careful research, and professional advice when needed can help you make decisions that fit your goals and circumstances.
frequently asked questions
Q1. What are the most common personal finance mistakes in your 30s?
Common finance mistakes include overspending, delaying emergency savings, carrying high-interest debt, neglecting retirement planning and investing without understanding the risks.
Q2. How much money should I save in my 30s?
The right amount depends on your income, essential expenses, debts, and goals. Start with an affordable monthly contribution and build an emergency fund that reflects your personal needs.
Q3. Is it too late to start saving for retirement at 35?
No. Starting at 35 still gives your retirement savings time to grow. Review the retirement options available in your country and contribute regularly according to your budget.
Q4. Should I pay off debt or invest first?
Paying down high-interest debt is often a strong priority because interest costs can outweigh uncertain investment gains. Keep essential payments current and consider your emergency savings and any available employer retirement match before deciding.
Q5. How can I improve my finances with a limited income?
Track your spending, prioritize essential bills, reduce avoidable costs where possible, and save small amounts consistently. If your income barely covers necessities, focus first on essential needs and realistic steps to improve cash flow.
Final Thoughts
Your 30s can provide an opportunity to strengthen your financial habits, but there is no single timeline that works for everyone. Your income, responsibilities, location, and personal goals all affect the choices available to you.
The most important step is to recognize the Finance Mistakes you can control and take practical action. Build a budget, save for emergencies, manage expensive debt, understand investment risks, review insurance, and set goals that match your needs.
You do not have to achieve everything in one year. Start where you are, make realistic changes, and review your progress regularly. Better finance mistakes decisions today can give you more options and greater confidence in the years ahead.
4 thoughts on “Personal Finance Mistakes to Avoid in Your 30s”