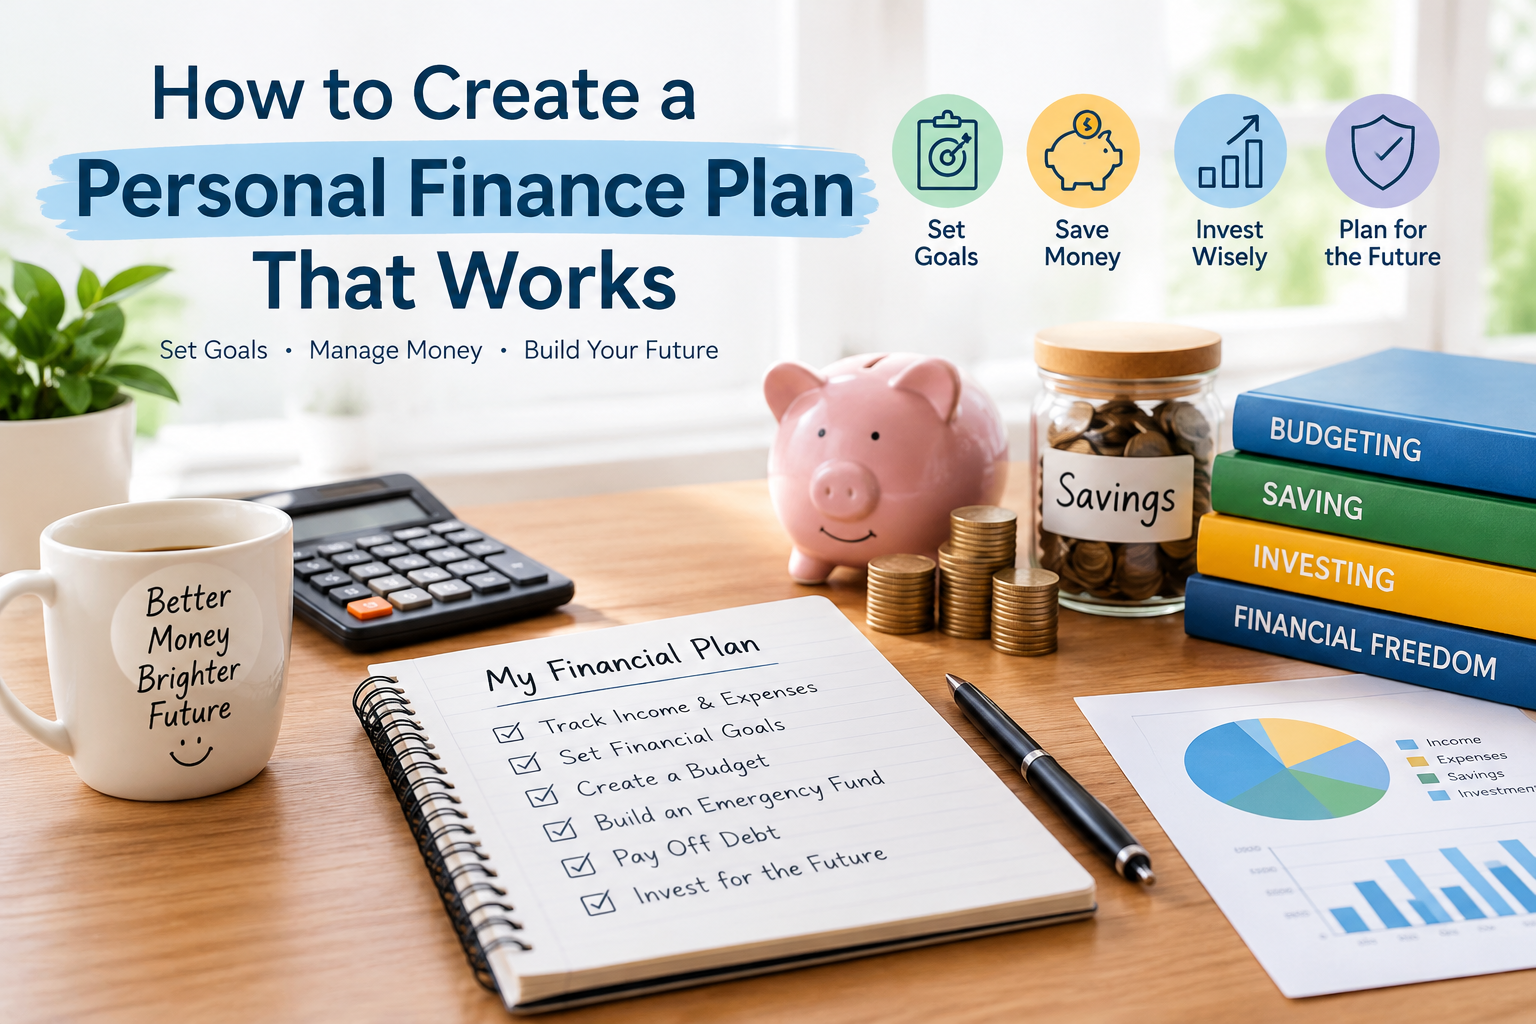
Managing money becomes easier when you have a clear plan. If you earn a regular salary, run a small business, work as a freelancer, or manage a household, knowing where your money goes can help you make better decisions. Without a plan, it is easy to spend too much, delay important goals or rely on debt when unexpected costs arise.
Good Finance plan can help you build better habits and take control of your money. However, a successful personal finance plan is not about following every money rule or cutting out everything you enjoy. It is about understanding your income, managing expenses, preparing for emergencies, reducing debt and saving for the future.
The right approach depends on your income, responsibilities, location, and financial goals. This guide explains how to create a practical plan that fits your life and how to adjust it as your circumstances change.
Understand Your Current Financial Situation
Before making a plan, understand how much money you earn, spend, owe and own. Start by listing your monthly income after taxes and other required deductions. Include reliable income from employment, freelance work, a business, or other sources. Next, review your expenses. Separate essential costs such as housing, food, utilities, transportation, and healthcare from optional spending such as entertainment, subscriptions and frequent shopping. Also list your debts, savings, investments, and other financial assets.
One of the most useful Finance plan is to track your spending for at least one month. Bank statements, receipts, and budgeting apps can help you identify patterns you may have overlooked. For example, if you earn $3,000 per month and spend $2,850, you have only $150 left before unexpected expenses. Knowing this gives you a clear starting point for improvement.
Set Clear and Realistic Financial Goals
A finance plan works better when you know what you want your money to achieve. Your goals might include paying off a credit card, building an emergency fund, buying a home, paying for education or preparing for retirement. Divide your goals into three groups. Short-term goals may take several months to achieve. Medium-term goals may require a few years. Long-term goals usually involve major life plans such as retirement or buying property.
Make each goal specific and measurable. Instead of saying you want to save more money, decide to save $1,200 over 12 months. That means setting aside $100 each month, provided your budget can support it. Practical Finance plan include prioritizing goals based on urgency and importance rather than trying to achieve everything at once. Write down your targets, set deadlines, and review your progress regularly.
Create a Monthly Budget That Fits Your Life
A budget helps you decide how to use your income before you spend it. One popular method is the 50/30/20 rule. It suggests allocating 50% of after-tax income to needs, 30% to wants, and 20% to savings and debt repayment. For someone earning $3,000 per month, this example would allocate $1,500 to needs, $900 to wants, and $600 to savings and debt repayment. These percentages are guidelines, not strict rules. In a high-cost city, essential expenses may take up more than half of your income. Someone with high-interest debt may also need to direct more money toward repayment.
Useful Finance plan include choosing a budgeting method you can maintain. If the 50/30/20 rule does not fit your situation, create your own categories based on actual costs. A zero-based budget is another option: assign every dollar a purpose until your income minus planned expenses equals zero. The aim is to make spending more intentional without creating a budget so restrictive that you cannot follow it.
Build an Emergency Fund
Unexpected expenses can disrupt even a well-planned budget. A medical bill, urgent home repair, vehicle problem, or temporary loss of income may force you to borrow money if you have no savings. An emergency fund provides a financial buffer. Start with a small target that feels achievable, then increase it over time. Some people aim to save enough to cover several months of essential expenses, but the right amount depends on job security, household needs, dependants, and access to other support.
For example, if your essential expenses are $1,800 per month, a three-month emergency fund would equal $5,400. You do not need to save this amount immediately. Setting aside $150 each month would build $1,800 in a year before interest.
Among the most practical Finance plan is to keep emergency money somewhere safe and accessible, such as an appropriate savings account. Check fees, withdrawal rules, interest rates and any deposit protection available in your country. The benefit is greater financial flexibility. The trade-off is that cash savings may earn less than long-term investments and may lose purchasing power when inflation exceeds the interest earned.
Make a Plan to Manage and Repay Debt
Debt can help people pay for important purchases, education, or property. However, high interest charges can make it harder to save and reach other goals. List every debt with its outstanding balance, interest rate, minimum payment, and due date. Continue making required minimum payments while deciding which balance to target with any extra money.
The debt avalanche method directs extra payments toward the debt with the highest interest rate first. This can reduce interest costs when other factors remain similar. The debt snowball method targets the smallest balance first, which may provide motivation through quicker progress.
For example, if you have a credit card charging a high interest rate and a lower-rate personal loan, paying extra toward the credit card may reduce borrowing costs. Keep making the required payment on the personal loan. Reliable Finance plan also include checking for early repayment fees, reviewing loan terms, and contacting lenders if you cannot meet your payments. Avoid taking on new expensive debt to cover routine spending whenever possible.
Start Saving and Investing for the Future
Once your basic expenses are covered and you have a strategy for expensive debt, consider how to fund longer-term goals. Savings accounts may suit emergency reserves and money needed soon. Investing may suit goals that are years away, depending on your risk tolerance and circumstances. Before investing, understand the available options, fees, taxes, and possible losses. Stocks, bonds, mutual funds, and exchange-traded funds have different features and risks.
Diversification can reduce the impact of poor performance in one investment, but it cannot eliminate investment risk or guarantee a profit. For example, money needed for rent or tuition next year generally should not depend on stock market performance. Retirement savings may allow a longer investment timeframe, although the appropriate approach varies by individual.
One of the most important Finance plan is to avoid investments promising guaranteed high returns with little or no risk. Research providers and check whether financial professionals are properly registered with the relevant regulator.
Protect Your Money and Review Your Progress
A personal finance plan should also protect you from financial setbacks. Review whether you need suitable health, life, home, vehicle, or other insurance based on your circumstances. Read policy exclusions, deductibles, coverage limits, and claim conditions before buying a policy. Protect your accounts by using strong passwords, enabling multifactor authentication where available and checking statements for unfamiliar transactions. Be cautious of unsolicited investment offers and requests for urgent payments.
Set a regular time each month to compare your budget with actual spending. Check whether your savings are growing, debt is falling, and bills are being paid on time. Update your plan after a change in income, a move, a new family responsibility, or another major life event. These Finance plan help keep your plan relevant rather than turning it into a document you create once and forget.
Practical Example: A Simple Personal Finance Plan
Imagine that your monthly take-home income is $3,000. Your essential expenses are $1,600, optional spending is $500, debt payments are $400, and savings are $300. Your total planned spending and allocations equal $2,800, leaving $200 unassigned. You could use that remaining amount to increase emergency savings, pay extra toward high-interest debt, or fund another priority. The best choice depends on your current savings, debt rates, and upcoming expenses.
This example is only a starting point. Your plan may need different amounts if you support dependants, have irregular income, face high housing costs, or live in a country with different taxes and financial products. The most effective Finance plan are those that help you make consistent progress without ignoring your real needs.
Frequently Asked Questions
Q1. What is a personal finance plan?
A personal finance plan is a strategy for managing income, expenses, savings, debt, investments and financial protection. It helps you set goals and decide how to use your money to achieve them.
Q2. How do I create a personal finance plan with a low income?
Start by tracking your income and essential expenses. Prioritize housing, food, utilities, and required debt payments. Save a small amount when possible and look for manageable ways to reduce costs or increase income. Adjust your plan as your circumstances improve.
Q3. What is the 50/30/20 budgeting rule?
The 50/30/20 rule is a budgeting guideline that allocates 50% of after-tax income to needs, 30% to wants, and 20% to savings and debt repayment. You can adjust these percentages to fit your income and living costs.
Q4. How much money should I keep in an emergency fund?
Your target depends on essential expenses, job stability, dependants, and other financial responsibilities. A common starting goal is to build enough savings for several months of essential costs. Begin with a smaller achievable amount if necessary.
Q5. How often should I review my personal finance plan?
Review your budget and progress every month. Revisit your broader financial goals at least once or twice a year and whenever your income, expenses, family responsibilities, or financial priorities change.
Final Thoughts
Creating a personal finance plan does not require a high income or complicated financial tools. It starts with understanding your current situation, setting realistic goals, preparing a workable budget, and building better money habits.
Use the Finance plan in this guide to make gradual improvements. Start with one or two changes, such as tracking your spending or setting up an automatic savings transfer. As your situation improves, work on debt repayment, emergency savings and long-term goals.
Remember that finance plan is an ongoing process. Your needs will change over time, so keep reviewing your progress and adjusting your plan. Consistent decisions can help you manage uncertainty and work toward greater financial stability.