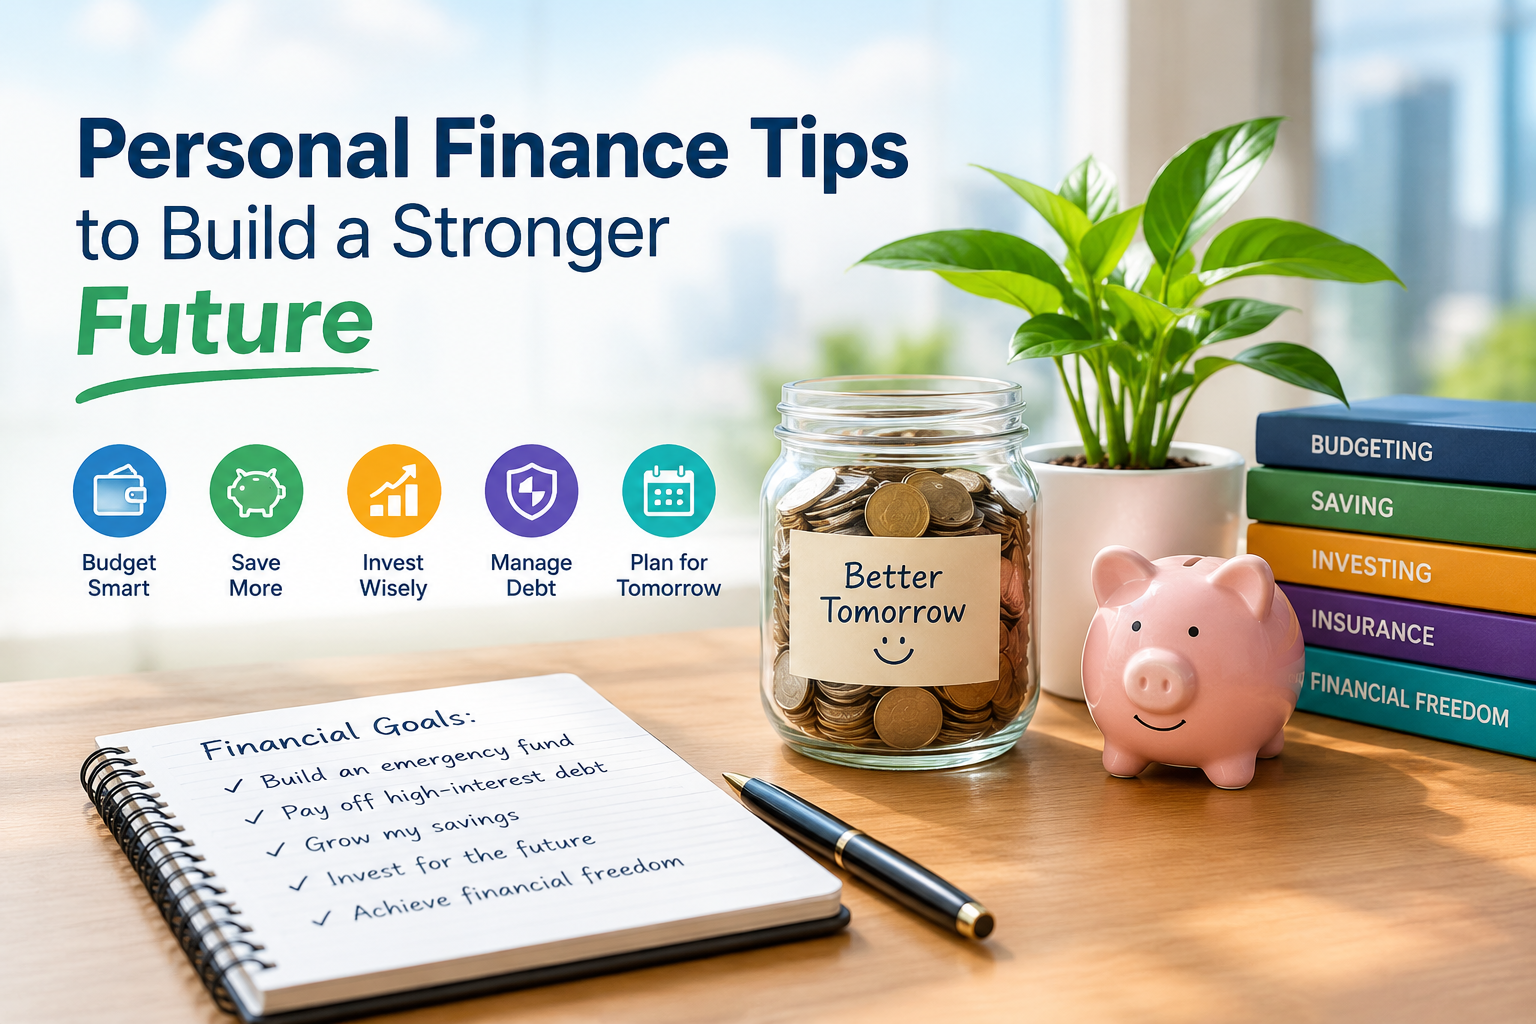
Managing money is an important part of building a stable future. If you earn a regular salary, work as a freelancer, run a small business or manage a household, the way you handle your income can affect your daily life and long-term goals. Good money habits can help you prepare for unexpected costs, reduce financial stress, and make better decisions about saving and investing.
The good news is that you do not need a high income to start improving your personal finances. Small steps such as tracking expenses, paying bills on time, and saving a set amount regularly can make a difference over time. The most useful Personal Finance Tips are the ones you can follow consistently and adjust as your circumstances change.
In this guide, you will learn practical ways to manage your money, build savings, handle debt, protect your income, and plan for the future.
Create a Realistic Monthly Budget
A budget gives you a clear picture of how much money you earn and where it goes. Without a plan, everyday spending can use up your income before you have a chance to save. A simple budget helps you cover essential costs while making room for future goals. Start by calculating your monthly income after taxes and other required deductions. Then list your regular expenses, including housing, food, transport, utilities, debt payments and insurance. Add variable costs such as clothing, entertainment, gifts and occasional repairs.
For example, if your monthly take-home income is $2,500, you could allocate $1,500 to essential expenses, $500 to savings and debt repayment, and $500 to flexible spending. These figures are only an illustration. Your actual budget should reflect your household costs, financial obligations and priorities. Review your spending at the end of each month. If your expenses are higher than your income, look for realistic changes rather than cutting every enjoyable activity. A personal finance budget works best when it is practical enough to follow over the long term.
Build an Emergency Fund
An emergency fund is money set aside for unexpected expenses such as medical bills, urgent home repairs, car problems, or a temporary loss of income. It can help you avoid borrowing money when life does not go according to plan. Start with a manageable target instead of waiting until you can save a large amount. Your first goal might be enough to cover one unexpected bill.
Once you reach that target, work toward saving several months of essential living expenses if your budget allows. For instance, saving $50 each month gives you $600 after one year, before any interest. If your income increases, you may be able to raise your monthly contribution. Keep emergency savings somewhere safe and accessible. A suitable bank savings account may be useful, depending on the protection offered in your country, withdrawal conditions, fees and interest rate.
Avoid placing money you may need immediately into volatile investments. The main benefit is greater personal finance flexibility. The challenge is that building an emergency fund takes time, especially when income is limited. Consistent small contributions are still a useful starting point.
Make Saving a Regular Habit
Saving becomes easier when you treat it as a planned expense rather than something you do only when money is left over. Set a realistic savings amount and transfer it to a separate account after receiving your income, provided you have enough to cover essential bills. You might begin by saving 5% of your income and increase the amount when your circumstances improve. If you earn $2,000 per month, 5% equals $100. If that amount is not affordable, start with $10 or $20 and build from there.
Automatic transfers can make saving more consistent. However, check your account balance and transfer dates to avoid overdraft charges or missed payments. It also helps to give each savings goal a purpose. You might save separately for emergencies, education, a home deposit, travel, or retirement. Clear goals make it easier to decide how much to save and when you may need the money.
Pay Down High-Interest Debt
Debt can make it harder to reach personal finance goals because interest and fees reduce the money available for other needs. Credit cards, payday loans, and some personal finance loans can carry high borrowing costs, so review your balances and interest rates carefully. One approach is the debt avalanche method. You make the required payments on all debts and put extra money toward the debt with the highest interest rate.
This can reduce total interest costs, assuming other terms remain comparable and you avoid taking on additional debt. Another option is the debt snowball method. You focus extra payments on the smallest balance first while maintaining required payments on other accounts. Paying off a small debt can provide motivation, although this approach may cost more in interest.
For example, if you owe $500 on one account and $2,000 on another, the best starting point depends partly on their interest rates and your need for motivation. Compare the costs before choosing. Do not ignore essential expenses or miss required payments to follow a repayment strategy. If you are struggling to meet minimum payments, contact your lender early and ask about available hardship arrangements.
Use Credit Responsibly
Credit can help people manage certain purchases and build a borrowing history, but it can also create personal finance pressure when used without a repayment plan. Before applying for a credit card or loan, understand its interest rate, fees, repayment rules, and penalties. Whenever possible, pay credit card balances in full by the due date to avoid interest on purchases under the terms of your card. Paying on time and keeping balances manageable can also support a healthy credit history in countries that use credit scoring systems.
Check your credit report periodically where this service is available. Look for unfamiliar accounts, incorrect balances, and payment records that appear wrong. Report errors to the relevant credit reporting agency or lender. Remember that credit reporting rules differ between countries. A credit score is not a complete measure of financial health and a good score does not mean you should borrow more than you can afford.
Start Investing With Clear Goals
Saving and investing serve different purposes. Savings are generally useful for short-term needs and emergencies, while investing may help you pursue longer-term goals. Investments can lose value, so money needed soon should not usually depend on stock market performance. Before investing, consider your time frame, ability to handle losses, existing debt, emergency savings, and local tax rules.
Learn about available investment options and compare their fees, risks, and liquidity. Diversification is another important principle. Spreading investments across different assets or sectors can reduce the impact of poor performance in one area, although it cannot eliminate investment risk or guarantee a profit.
For example, someone saving for a home deposit needed in two years may prefer accessible lower-risk savings options. Someone personal finance planning for retirement several decades away may be able to consider a diversified long-term investment portfolio, depending on their situation. Be cautious of anyone promising guaranteed high returns or pressuring you to invest quickly. Research the provider and understand the product before committing money.
Protect Your personal Finances With Suitable Insurance
Personal finance planning is not only about saving and growing money. It also means preparing for events that could create large expenses or reduce your income. Depending on your circumstances, suitable health, life, home, car, travel, or disability-related insurance may help manage certain risks. Start by identifying the losses you could not comfortably afford to cover yourself. Then compare policies, premiums, deductibles, coverage limits, exclusions and claim requirements.
For example, a household that depends on one person’s income may need to consider how it would manage if that person died or became unable to work. A homeowner may need protection against specific property risks, while a frequent traveller may benefit from suitable travel coverage.
Insurance has costs and limitations. Not every policy covers every event, and exclusions can be important. Read the terms carefully and choose coverage based on your actual needs rather than buying every available product.
Set Financial Goals and Review Your Progress
Financial goals give your money a clear direction. Without them, saving and spending decisions can become reactive. Separate your goals into short-term, medium-term, and long-term plans. Short-term goals may include building an emergency fund or paying off a small debt. Medium-term goals might involve education or a home deposit. Long-term goals may include retirement or supporting family members.
Make each goal specific and measurable. Instead of saying you want to save more, set a target of saving $1,200 over twelve months. That would require an average contribution of $100 per month, assuming no interest or withdrawals. Review your budget, savings, debts, and investments every few months. Update your plan when your income changes, your household grows or your priorities shift. A personal finance plan should support your life, not become a source of constant pressure.
Improve Your Financial Knowledge
Financial products and rules can be complicated, especially when comparing loans, insurance, investment accounts, and retirement options. Taking time to learn the basics can help you ask better questions and avoid costly mistakes. Use reliable educational resources from government agencies, financial regulators and established consumer protection organisations. Check the date of information and confirm that it applies to your country. Tax rules, deposit protection, credit reporting, and investment regulations vary across markets.
You can also use budgeting tools or spreadsheets to track spending and calculate savings targets. Keep your personal finance information secure, use strong passwords, and be cautious with unsolicited messages requesting account details. Avoid making major decisions based only on social media posts or advice from someone who does not understand your circumstances. When a decision involves complex taxes, investments, debt or insurance, consider consulting a qualified professional who is authorised to provide advice in your jurisdiction.
Frequently Asked Questions
Q1. What are the most important personal finance tips for beginners?
Start by tracking your income and expenses, creating a realistic budget, building emergency savings, paying bills on time, and managing high-interest debt. Once your immediate needs are covered, begin personal finance planning for longer-term goals such as retirement.
Q2. How much money should I save each month?
There is no single amount that works for everyone. Your savings target depends on your income, essential expenses, debts, and goals. You could begin with a small fixed amount or a percentage of your income and increase it when affordable.
Q3. How much should I keep in an emergency fund?
Your target depends on your essential expenses, job security, health needs, and other sources of support. Some people aim to build a reserve covering several months of essential costs. Start with a smaller achievable target if saving that much is not currently possible.
Q4. Should I pay off debt or invest first?
Consider paying down high-interest debt before investing additional money because interest charges can be costly. At the same time, maintain essential payments and consider building a basic emergency reserve. The right balance depends on interest rates, employer retirement benefits, and your personal finance circumstances.
Q5. How can I improve my financial situation on a low income?
Track essential spending, look for manageable ways to reduce costs, avoid expensive borrowing where possible and save small amounts consistently when you can. If your income does not cover essential expenses, focus first on immediate needs and investigate eligible local assistance or debt support services.
Final Thoughts
Building a stronger financial future does not require perfect decisions or a large income. It starts with understanding your money and making steady improvements. A realistic budget can help you control spending, regular savings can prepare you for emergencies, and a clear debt repayment plan can reduce borrowing costs. Investing and suitable insurance can also play important roles when they match your goals and financial circumstances.
Choose one or two habits to improve first. You might track your expenses this month, start an emergency fund, or review the interest rates on your debts. Once those habits become part of your routine, move on to the next goal.
The most effective Personal Finance Tips are practical, consistent, and suited to your life. Review your progress regularly, learn from setbacks, and adjust your plan when your circumstances change. Small steps taken over time can help you build greater financial stability and prepare for the future with more confidence.
1 thought on “Personal Finance Tips to Build a Stronger Future”