Introduction
Managing money can feel difficult when monthly bills keep increasing and unexpected expenses appear. Whether you earn a regular salary, work as a freelancer, run a small business or manage a household, having a clear spending plan can make everyday financial decisions easier. The good news is that you do not need a high income or complicated financial software to get started.
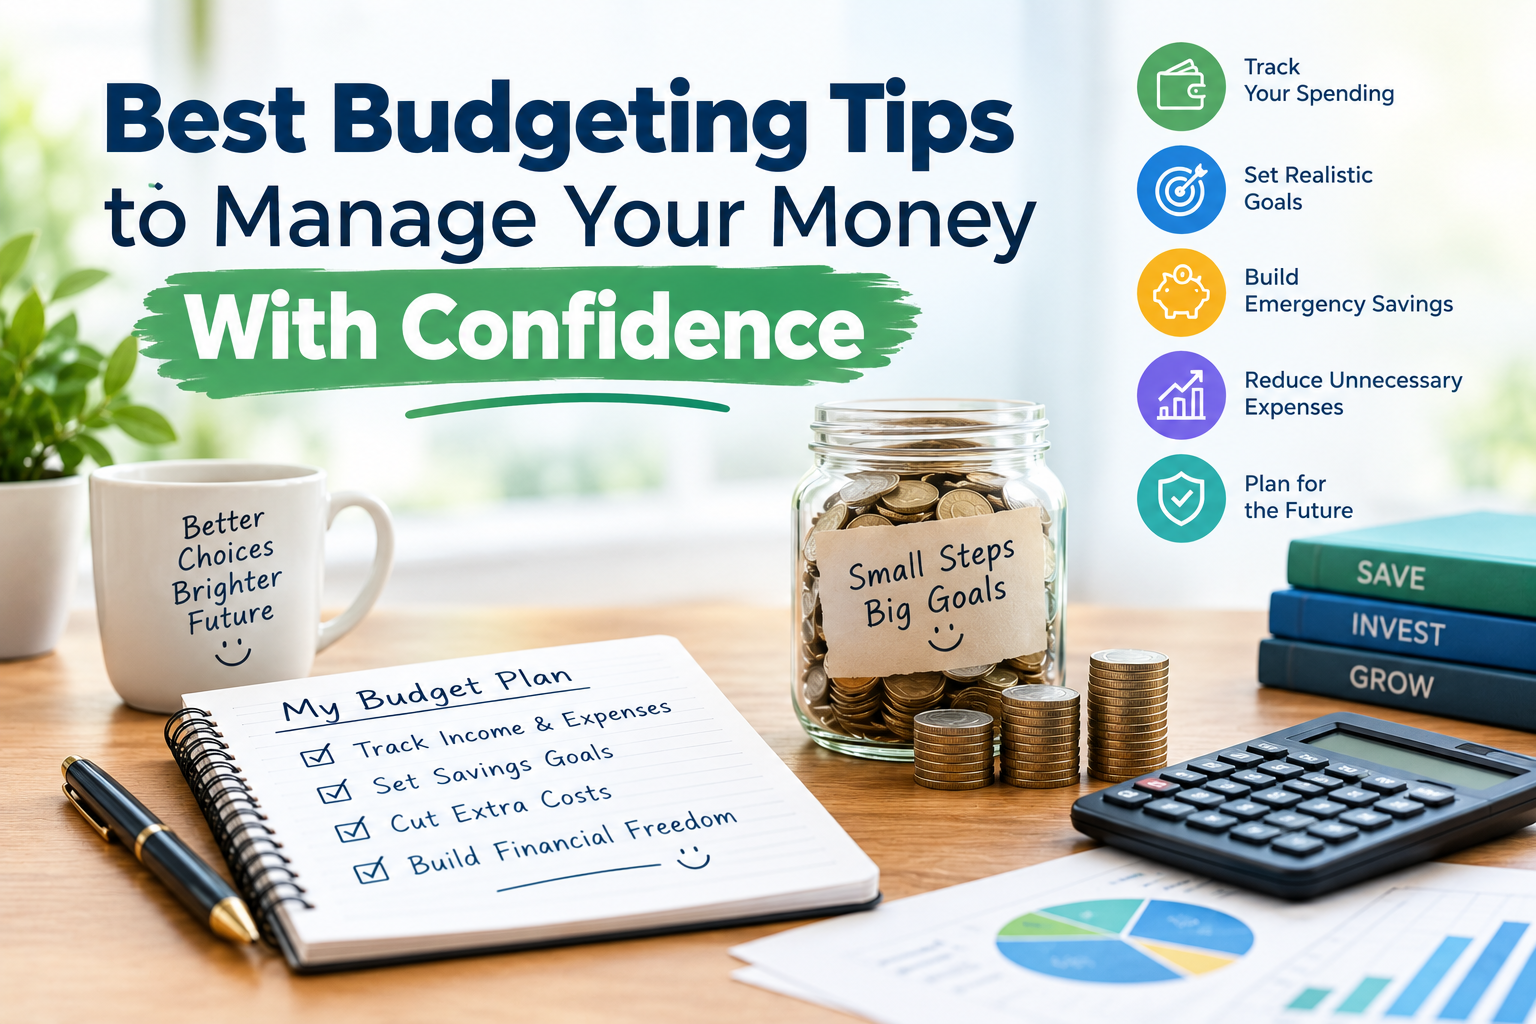
The right Budgeting Tips can help you understand where your money goes, control unnecessary spending, prepare for emergencies, and work toward your financial goals. A budget is not about removing every enjoyable expense from your life. Instead, it helps you decide what matters most and use your income more carefully.
In this guide, you will learn practical Budgeting Tips that work with different income levels and lifestyles. You will also find examples to help you create a realistic budget, manage changing expenses, and build better money habits over time.
Understand Your Monthly Income
The first step toward better money management is knowing how much money you actually have available. Your budget should be based on your take-home income after taxes and other required deductions rather than your full salary. If you receive money from several sources, such as employment, freelance projects, rental income or a small business, calculate a realistic monthly total. For irregular earnings use previous income records to estimate a conservative amount instead of assuming every month will be equally profitable.
For example, if your monthly take-home income is $2,500, use that amount as your starting point. If your earnings change from month to month, build your regular spending plan around a cautious estimate and adjust it when your actual income arrives. These Budgeting Tips help prevent you from committing money that may not be available when your bills are due.
Track Every Expense
You cannot manage your money effectively if you do not know where it goes. Tracking your spending for at least one month can reveal patterns that are easy to overlook. Record essential costs such as rent, groceries, utilities, transportation, insurance, and debt payments. Also include smaller purchases such as takeaway meals, digital subscriptions, snacks and online shopping. You can track expenses using a spreadsheet, a notebook, a budgeting application, or your bank statements. Choose a method that is simple enough to maintain.
For instance, spending $5 on a small purchase five days a week adds up to approximately $100 over four weeks. You may decide the expense is worthwhile but seeing the total helps you make an informed choice. Among the most useful Budgeting Tips is to review your spending without judging yourself. The purpose is to identify opportunities for improvement, not to feel guilty about every purchase.
Separate Needs From Wants
One of the most practical Budgeting Tips is learning to distinguish essential expenses from optional spending. Needs generally include housing, basic food, necessary transportation, utilities, essential healthcare, and minimum debt payments. Wants may include entertainment, premium subscriptions, restaurant meals, and nonessential upgrades.
However, the difference depends on your circumstances. Internet access may be essential for someone working remotely, while a particular streaming service is usually optional. Before making a purchase, ask yourself whether it supports an essential need, an important goal or simply a temporary desire. You do not have to eliminate every want. Instead, decide how much you can comfortably spend after covering your priorities.
This approach makes budgeting more flexible and sustainable because it leaves room for enjoyment while protecting your essential financial needs.
Choose a Budgeting Method That Fits Your Life
Different people need different ways to organize their money. The best method is one you understand and can follow consistently.
Try the 50/30/20 Budget Rule
The 50/30/20 method divides after-tax income into three broad groups: 50% for needs, 30% for wants, and 20% for savings and debt repayment beyond minimum obligations. For someone earning $2,500 per month, this would mean $1,250 for needs, $750 for wants, and $500 for savings and additional debt payments.
These percentages are guidelines, not strict requirements. If housing costs are high or your income is limited, you may need to spend more than 50% on necessities.
Consider Zero-Based Budgeting
Zero-based budgeting assigns every unit of income a purpose, including bills, spending, savings, and debt payments. The goal is for planned income minus planned expenses to equal zero. This does not mean spending all your money. Savings and emergency fund contributions are also assigned purposes.
These Budgeting Tips can help you choose a structure that suits your priorities rather than following a rule that does not fit your circumstances.
Set Realistic Savings Goals
Saving becomes easier when you know what the money is for. Your goals might include building an emergency fund, replacing an old vehicle, paying for education, buying a home or preparing for retirement. Start with a manageable target. For example, saving $25 each week would produce $1,300 over 52 weeks before interest, provided you maintain the contributions.
An emergency fund can help cover unexpected repairs, medical expenses, or temporary income loss without relying entirely on credit. The appropriate target depends on your household costs, job stability, dependants and access to other support. You do not need to reach a large target immediately. Begin with an amount you can afford and increase it when your financial situation improves.
Practical Budgeting Tips include treating savings as a planned expense rather than waiting to see whether money remains at the end of the month. The Consumer Financial Protection Bureau offers useful guidance on building an emergency fund.
Reduce Unnecessary Monthly Expenses
Review recurring payments regularly to find costs you can reduce without harming your quality of life. Small changes can create useful savings when they are repeated over time. Start by checking subscriptions, mobile plans, internet packages, bank fees, insurance policies, and frequent convenience purchases. Cancel services you no longer use and compare alternatives before renewing expensive contracts.
For example, suppose you identify a $12 subscription you rarely use and reduce other optional spending by $18 each month. You could free up $30 monthly, or $360 over a year. However, do not cancel essential insurance or choose a policy based only on its lowest premium. A cheaper option may provide less protection or have a higher deductible. Effective Budgeting Tips focus on reducing low-value spending while protecting important needs, financial security, and long-term priorities.
Plan for Irregular and Unexpected Expenses
Many budgets fail because they account for monthly bills but ignore costs that occur occasionally. Annual insurance payments, school expenses, vehicle maintenance, gifts and home repairs can put pressure on your finances when they arrive unexpectedly. Make a list of predictable nonmonthly costs and estimate their annual totals. Divide each amount by 12 to calculate a monthly saving target.
For example, if you expect $600 in annual vehicle maintenance and registration costs, setting aside $50 per month can help you prepare. Unexpected emergencies require a separate reserve where possible. If you cannot save much initially, start with a small contribution and increase it as your budget allows. These Budgeting Tips can reduce the need to borrow when an expense arrives. Remember that savings goals must remain realistic, especially when essential bills already consume most of your income.
Manage Debt Without Ignoring Essential Bills
Debt payments should have a clear place in your budget. Start by listing outstanding balances, interest rates, minimum payments and due dates. Pay required minimums on time where possible, then consider directing additional money toward your highest-interest debt. This approach can reduce interest costs, although your results depend on your loan terms, fees and repayment consistency.
Another option is the debt snowball method, which focuses on the smallest balance first. Some people find that early progress helps them stay motivated, even if it does not always minimize total interest. If you cannot afford essential bills or minimum payments, contact your lender or a reputable nonprofit debt adviser to discuss available options. Useful Budgeting Tips should help you compare repayment strategies without encouraging you to skip essential expenses or take on new high-cost borrowing.
Review Your Budget Every Month
A budget is a working plan, not a permanent set of rules. Your income, living costs, family needs, and financial goals can change over time. Set aside 15 to 30 minutes each month to compare planned spending with actual transactions. Identify categories where you spent more than expected and decide whether to adjust your habits or revise the plan.
For example, higher winter heating bills may require a larger utilities allowance. If your freelance income falls, you may need to reduce optional spending until earnings recover. You can also review your progress toward savings goals and increase contributions when affordable. These Budgeting Tips help you respond to changing circumstances instead of abandoning your entire plan after one difficult month.
Use Budgeting Tools Carefully
Spreadsheets, banking dashboards, expense trackers, and budgeting applications can make it easier to organize financial information. Choose tools based on your needs, available features, cost and privacy protections. Before connecting a financial account to an application, check its reputation, data access permissions, security practices, and cancellation process. Avoid sharing banking passwords with unverified services.
A simple spreadsheet may be enough if you prefer to record transactions manually. Someone managing several accounts may benefit from automated categorization, provided the tool is reliable. The best Budgeting Tips emphasize consistency over complexity. A basic system you use every week is generally more helpful than an advanced application you stop using after a few days.
Benefits and Limitations of Budgeting
Following a budget can improve awareness of spending, support savings goals, reduce avoidable fees, and help you prepare for financial surprises. It can also make discussions about shared household expenses clearer. However, budgeting cannot solve every financial problem. If your income is too low to cover essential living costs, cutting small purchases may not be enough.
You may need to explore additional income, eligible assistance, payment arrangements or professional debt advice. Unexpected expenses can also disrupt even a well-prepared plan. Leave room for adjustments and avoid treating every budget shortfall as a personal failure. The purpose of Budgeting Tips is to help you make informed choices with the resources available to you, not to promise financial success or eliminate every risk.
Frequently Asked Questions
Q1. What are the best budgeting tips for beginners?
Start by calculating your take-home income, tracking expenses, separating needs from wants and setting realistic savings goals. Choose a simple budgeting method and review your progress monthly.
Q2. What is the 50/30/20 budgeting rule?
It is a guideline that allocates 50% of after-tax income to needs, 30% to wants and 20% to savings and additional debt repayment. Adjust the percentages to suit your income and living costs.
Q3. How can I budget with a low income?
Prioritize housing, food, utilities, healthcare, transportation and required debt payments. Track spending, look for meaningful cost reductions and save small amounts when possible. If essential costs exceed your income, consider reputable local support services.
Q4. How often should I review my budget?
Review your spending regularly and complete a more detailed check at the end of each month. Revisit your plan whenever your income, household circumstances or major expenses change.
Q5. Should I save money or pay off debt first?
The right choice depends on your debt interest rates, emergency savings and financial stability. Maintain required payments, consider building a small emergency reserve and prioritize expensive debt where appropriate. Compare the costs and risks before making a decision.
Final Thoughts
Managing money with confidence starts with understanding your income, tracking your spending, and making realistic choices. You do not need a perfect budget from day one. You need a practical system that reflects your responsibilities, goals, and everyday life.
Start with two or three changes, such as recording expenses, reviewing subscriptions, or setting aside a small amount each payday. As these habits become easier, you can improve your plan and prepare for larger financial goals.
The most effective Budgeting Tips are the ones you can maintain over time. Stay flexible, learn from each month’s results and remember that steady progress matters more than perfection.
2 thoughts on “Best Budgeting Tips to Manage Your Money With Confidence”